Breadcrumbs
These links will help you get back to where you want to go faster.
How to Effectively Claim Hail Damage on Your Roof in Rio Rico, Arizona: Deadlines, Coverage, and Expert Guidance
Living in Rio Rico, Arizona, means enjoying abundant sunshine but also preparing for sudden, severe storms during monsoon season. Among these, hailstorms pose a significant risk to your roof’s integrity, often causing damage that’s not immediately visible. Understanding how to spot hail damage, navigate insurance policies, and act within critical deadlines is essential to protecting your home and finances. This comprehensive guide equips Rio Rico homeowners with practical insights—from identifying hail damage to successfully filing insurance claims—with expert advice from trusted local professionals like Advanced Roofing, LLC.
Looking for a roofing contractor near you for a shingle roof, flat roof, foam roof, tile refelt, or tile roof installation? We are roof insurance claim specialists that are licensed, bonded, and insured. Our roofing company offers both residential and commercial roofing services. We serve Gilbert Arizona, Phoenix Metro and Rio Rico, Arizona. Call 602-350-4052 or 520-264-8776 or schedule an appointment online for a free roof inspection.
What you will learn in this article:
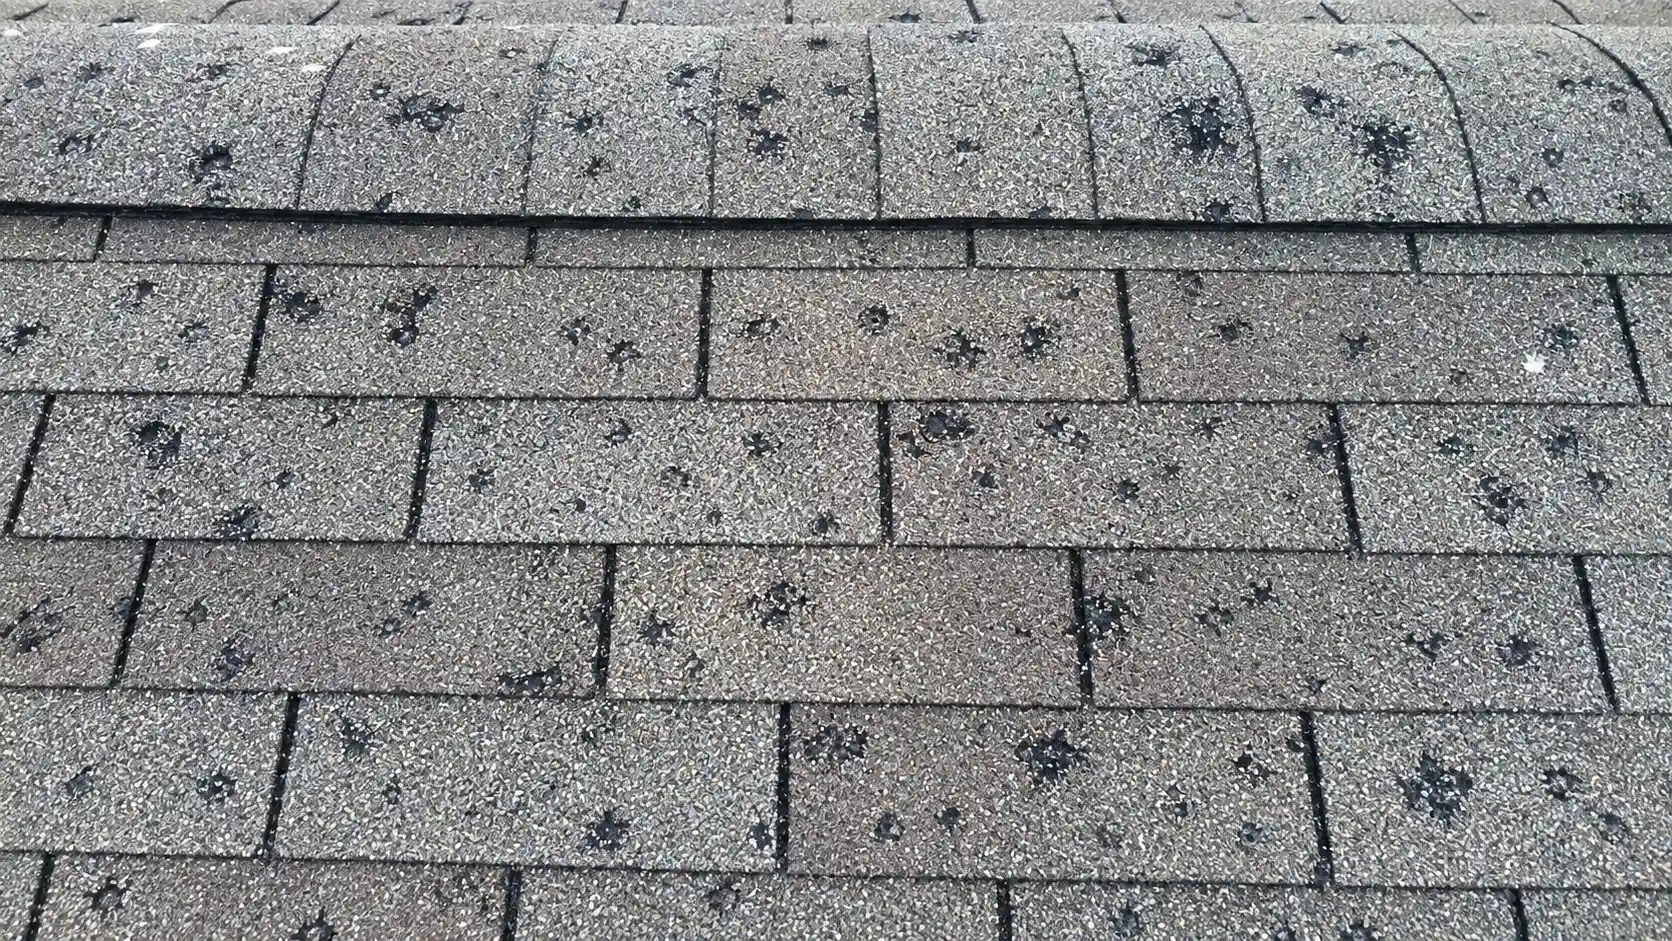
– Hail damage may not be visible at first, often revealing leaks or wear later. Look for signs such as granule loss, cracked shingles, dents in metal parts, and punctures in foam roofs. A professional inspection is essential to distinguish hail damage, which tends to cluster on storm-facing slopes, from normal wear and tear.
– Most Arizona homeowner insurance policies cover sudden hail damage, but coverage depends on the policy type: Replacement Cost Value (RCV) covers full roof replacement without depreciation deductions, while Actual Cash Value (ACV) deducts depreciation, resulting in lower payouts, especially for older roofs.
– Deductibles, usually 1-2% of the home’s insured value, apply, and cosmetic damage that doesn’t affect waterproofing may be excluded.
– Full roof replacement coverage may be provided if structural integrity is compromised or damaged shingles or tiles cannot be matched.
– Hail damage claims should be reported promptly, typically within 60 to 90 days of discovery; legal action against insurers usually must be filed within one year.
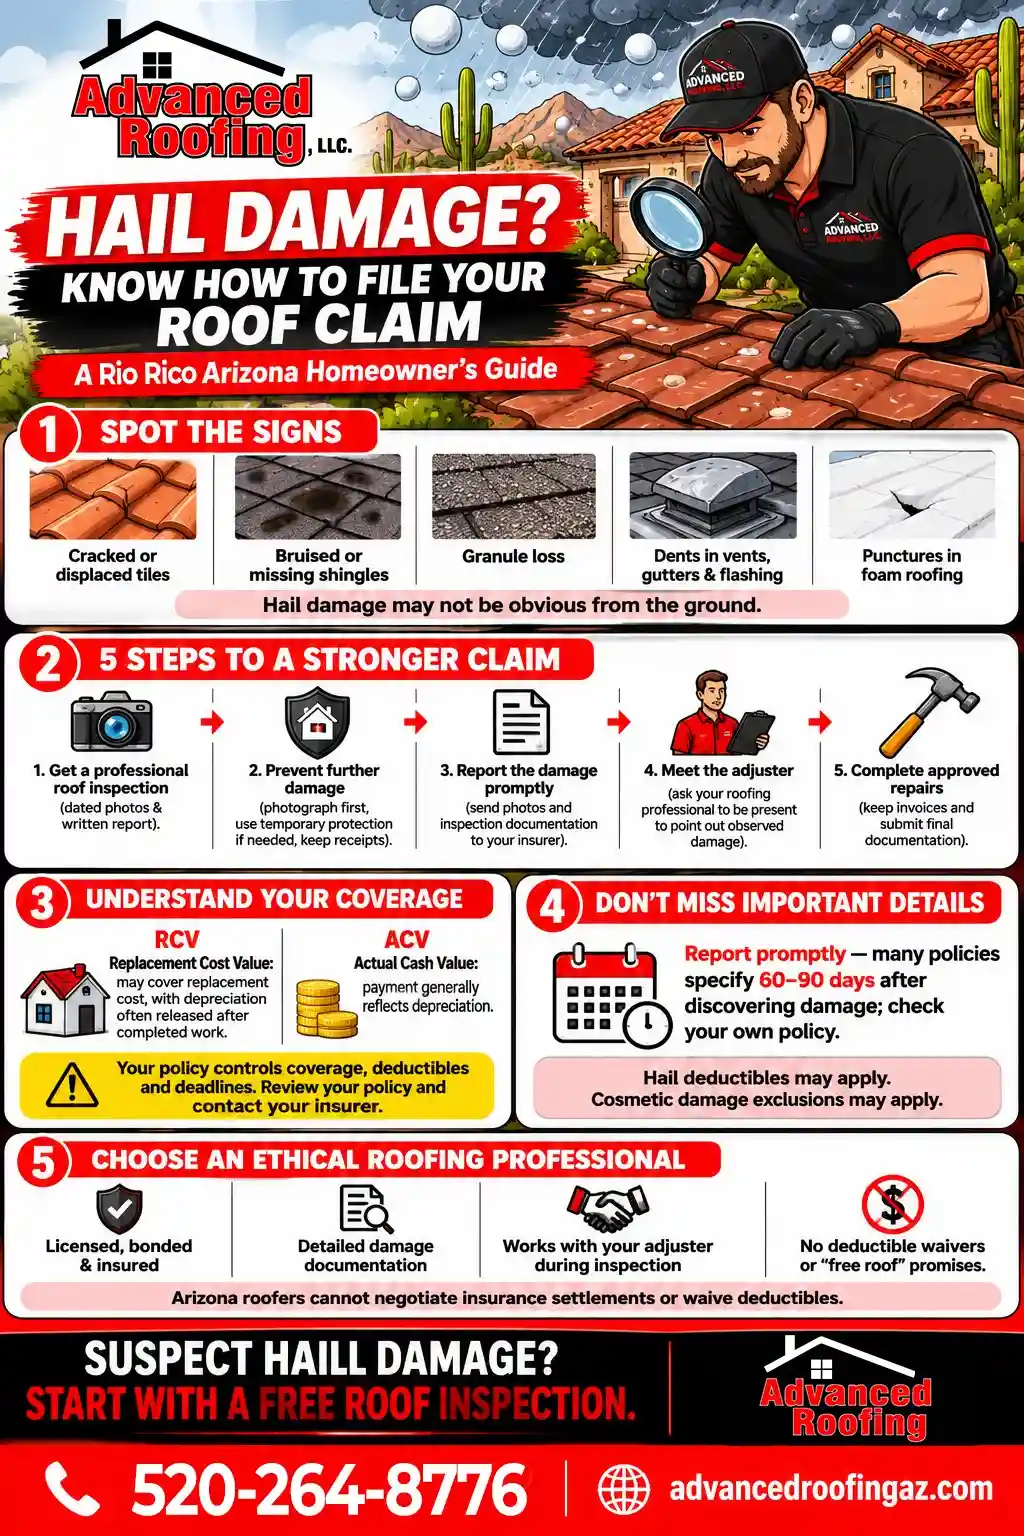
– Step-by-step claim process for hail damage.
– Arizona law prohibits roofers from negotiating settlements or waiving deductibles; be wary of unethical contractors offering “free roofs” or deductible waivers.
– Key insurance tips for Gilbert homeowners: Storm damage is covered while wear and tear is not. Compare deductibles with repair costs before filing a claim. Know whether your policy is ACV or RCV. Meet claim deadlines and hire reputable, ethical contractors.
Identifying Hail Damage on Your Roof
Hail damage often goes unnoticed at first glance, making early detection difficult yet crucial. While a roof struck by hail may appear intact from the ground or driveway, damage can manifest over weeks or months through leaks or material degradation. Recognizing the signs early can prevent costly repairs and insurance claim complications.
Key Signs of Hail Damage
- Granule Loss: Hail can dislodge protective ceramic granules from asphalt shingles, compromising UV resistance and accelerating deterioration.
- Cracked or Bruised Shingles and Tiles: Concrete tiles frequently crack or chip upon impact, while asphalt shingles may develop bruises unseen from above, weakening their waterproof barrier.
- Dents in Soft Metal Components: Dings on vents, gutters, flashing, and air conditioning fins provide visible, physical proof of hail impacts during recent storms.
- Punctures in Foam Roofing: Small but critical penetrations can reduce waterproofing effectiveness on foam roofs.
Distinguishing hail damage from natural aging or wear is essential for a valid insurance claim. Storm damage tends to cluster on areas exposed directly to hail, while typical weathering appears uniformly over time. A professional roofer’s detailed inspection, including photographic evidence and impact mapping, is invaluable to confirm hail damage and support your claim.
Understanding Your Insurance Coverage for Hail Damage in Arizona
Most homeowner insurance policies in Arizona cover sudden and accidental hail damage, but knowing the details of your coverage is vital to maximizing reimbursement. Several policy features affect how much you receive and what qualifies for a claim.
Additionally, displaced tiles pose safety hazards from falling debris, making swift emergency repairs a necessity following storms.
Request a Free Roof Inspection
Get a no-hassle no-obligation estimate by on of our emergency storm damage specialists on the cost to repair or place your roof.

Looking for a roofing contractor near you for a shingle roof, flat roof, foam roof, tile refelt, or tile roof installation? We are roof insurance claim specialists that are licensed, bonded, and insured. Our roofing company offers both residential and commercial roofing services. We serve Gilbert Arizona, Phoenix Metro and Rio Rico, Arizona. Call 602-350-4052 or 520-264-8776 or schedule an appointment online for a free roof inspection.
Replacement Cost Value (RCV) vs. Actual Cash Value (ACV)
Your policy’s valuation method determines your compensation for roof repairs or replacements. RCV policies pay for new materials and labor to restore your roof, often releasing withheld depreciation only after repairs are completed and paid in full. Conversely, ACV policies deduct depreciation upfront, providing compensation based on the current market value of your roof’s worn materials—meaning older roofs typically receive lower payouts.
Deductibles and Coverage Limitations
Hail damage claims are subject to deductibles that commonly range between 1-2% of your home’s insured value in Arizona. For example, on a $400,000 insured home, a 2% deductible requires $8,000 out-of-pocket before insurance coverage begins. Additionally, many policies exclude claims for purely cosmetic damage—such as minor dents or granule loss—that does not impair the roof’s waterproof function. Functional damage, like cracked tiles or missing shingles, usually qualifies for coverage.
When Is Full Roof Replacement Covered?
Insurers may approve a full roof replacement when hail damage compromises structural integrity or when damaged tiles or shingles cannot be matched with existing materials. Maintaining uniformity across the roof often necessitates replacing the entire surface rather than partial repairs.
Critical Timelines for Filing Hail Damage Claims
While Arizona lacks a statewide mandate defining claim reporting deadlines, your homeowner’s insurance policy typically specifies important timeframes. Adhering to these deadlines is crucial to avoid denial or disputes.
Reporting Your Claim Promptly
Policies usually require you to report hail damage “as soon as practicable,” often within 60 to 90 days of discovering the damage. Note that this window typically begins when you first notice damage—or its effects—not the date of the storm itself. Timely reporting helps ensure your claim is investigated while damage is fresh and clearly attributable to the hail event.
Legal Deadlines for Disputes
Arizona law and insurance contracts generally set a one-year period to initiate legal action if your claim is denied or underpaid. This time limit, often enforced through a “Suit Against Us” clause, demands prompt resolution or preparation to protect your rights.


A Step-by-Step Process to File Your Hail Damage Claim
Following a clear, organized approach can improve your chances for a fair insurance payout and minimize stress. Here is an effective, proven workflow:
1. Schedule a Licensed Roofer’s Free Inspection
Begin with a professional, comprehensive roof inspection to confirm hail damage and obtain detailed documentation. This report should include dated photographs, a written damage assessment, and, if required, an itemized repair estimate. Accurate, timely documentation strengthens your claim and prevents unnecessary filings that could negatively impact your insurance record.
2. Take Immediate Steps to Protect Your Property
Prevent further deterioration with temporary fixes like tarping if leaks are present. Photograph all affected areas before repairs and maintain detailed receipts. Most insurance policies reimburse reasonable emergency expenses incurred to mitigate damage.
3. Submit Your Claim with Complete Documentation
File your claim promptly, attaching the roofer’s inspection report, roof photos, and notes about the hail event. Clear, organized evidence expedites the adjuster’s evaluation and reduces disputes during the claim process.
4. Coordinate the Adjuster’s Inspection
Invite your roofer to accompany the insurance adjuster during their on-site evaluation to highlight visible hail damage and estimated repairs. Collaborative inspections reduce the risk of overlooked damage or underestimated repair costs.
5. Complete Repairs and Finalize Your Claim
After insurer approval, complete roof repairs promptly and submit the final invoice. For RCV policies, this triggers payment of any withheld depreciation, ensuring you receive full entitled reimbursement.
How Roofing Professionals Accurately Document Hail Damage
Insurance adjusters require clear, objective proof to validate hail damage claims. Professional roofers employ standardized methods, such as marking out 10×10-foot test squares on each roof slope and counting hail strike impacts. They examine soft metal fixtures for dents, photograph roofs with timestamps, and prepare detailed reports. This systematic approach provides strong evidence to support claims and resolve disputes efficiently.
Recognizing and Avoiding Contractor Pitfalls
While roofing contractors are vital allies in preparing your claim, Arizona law limits their involvement in insurance settlements. Roofers cannot negotiate directly with insurers or waive your deductible. Be wary of contractors offering “free roofs” or deductible waivers—such promises often indicate unethical or unlawful practices. If negotiation help is needed, consider hiring a licensed public adjuster who specializes in advocating for homeowners.
Essential Insurance Tips for Rio Rico Homeowners
| Concept | Meaning | Practical Advice |
|---|---|---|
| Storm Damage vs. Wear & Tear | Insurance covers sudden storm-induced damage, not gradual aging. | Obtain professional inspections to differentiate hail damage from normal roof wear. |
| Deductibles | Out-of-pocket amount before insurance payout starts. | Assess repair costs against your deductible; consider paying repairs yourself if below deductible to avoid premium hikes. |
| ACV vs. RCV Coverage | ACV reimburses current depreciated value; RCV covers full replacement cost. | Review your policy declaration page to confirm coverage type and plan accordingly. |
| Claim Filing Deadlines | Claims typically must be reported within 60-90 days; lawsuits filed within one year. | Report damage immediately and keep organized records to meet deadlines. |
| Contractor Ethics | Roofers assist with damage documentation but cannot negotiate settlements or waivers. | Choose reputable contractors; avoid offers of “free roofs” or deductible rebates. |
Why Choose Advanced Roofing, LLC for Your Rio Rico Roof Claim?
Advanced Roofing, LLC specializes in guiding Rio Rico homeowners through every stage of the hail damage claim process. Their expertise ensures thorough documentation, effective communication with insurance adjusters, and adherence to legal requirements. Clients benefit from free, no-obligation roof inspections, trusted advice, and quality restoration that safeguards homes against future storms. Partnering with Advanced Roofing means securing professional support dedicated to maximizing your insurance payout and protecting your home investment.
Protect Your Rio Rico Home by Acting Swiftly
Hail damage, often hidden beneath the surface, can seriously undermine your roof’s reliability and home safety if left unchecked. Because insurance timelines are strict, Rio Rico homeowners should prioritize scheduling expert roof inspections, filing claims promptly, and collaborating with knowledgeable professionals throughout the process. Thoroughly understanding your policy, meticulously documenting damage, and following a strategic claim workflow significantly increase the likelihood of a fair, full insurance settlement. Taking swift, informed action today can save you substantial expense and stress tomorrow—protect your home, your investment, and your peace of mind by partnering with specialists who understand hail damage claims inside and out.
Looking for a roofing contractor near you for a shingle roof, flat roof, foam roof, tile refelt, or tile roof installation? We are roof insurance claim specialists that are licensed, bonded, and insured. Our roofing company offers both residential and commercial roofing services. We serve Gilbert Arizona, Phoenix Metro and Rio Rico, Arizona. Call 602-350-4052 or 520-264-8776 or schedule an appointment online for a free roof inspection.
FAQs Frequently Asked Questions
How can I recognize hail damage on my roof in Rio Rico, Arizona?
Does homeowners insurance in Arizona typically cover hail damage to roofs?
What is the difference between Replacement Cost Value (RCV) and Actual Cash Value (ACV) coverage for hail damage?
Are deductibles required for hail damage claims, and how much are they?
How soon must I report hail damage to my insurance company in Arizona?
Can roofing contractors negotiate insurance settlements or waive deductibles for hail damage claims?
What steps should I take after discovering hail damage to maximize my insurance claim success?
When would an insurance policy cover full roof replacement after hail damage?
How do roofing professionals typically document hail damage for insurance claims?
What should I consider when choosing a contractor to help with my hail damage claim?
Find a Roofer Near Me Rio Rico Arizona
Not what you are looking for?
Design your roof using our Owens Corning Pick Your Shingles software or learn more about roofing using our Roofing Glossary or Roofing FAQs pages.
Get an Advanced New Roof Installation
Advanced Roofing, LLC. ensures that the roofing contractors hold necessary certifications and licenses required by Arizona Law & Registrar of Contractors ROC# 311509. Our Owens Corning certification is from the manufacturer – this indicates our expertise and commitment to quality, professionalism and that we hold ourselves to a high standard. Craftsmanship over salesmanship as we like to say.
We have the necessary insurance coverage, including liability and workers’ compensation. This protects both the contractor and the building owner from potential liabilities in case of accidents or property damage during the project. If you want more information, just call us and talk with the owner Mark Muzio: 602-350-4052.
Limited & lifetime warranties are provided by the contractor for both materials and workmanship. Additionally, ask us about commercial roofing maintenance services to ensure the long-term performance and durability of the commercial roof. In the event of a roof leak or damage, prompt action is essential to prevent further deterioration and minimize potential losses. Commercial buildings with flat roofs require specific considerations for emergency repairs and replacement.
Emergency roof repair is something we specialize in. We have seen and fixed bad work from other contractors and will tell you that it is important to make the right choice the first time. We will assess the extent of the damage and provide immediate solutions to mitigate further water infiltration. Temporary measures, such as tarping or patching, may be implemented until a permanent repair can be executed.
When replacing a roof, consider the existing roofing material, building structure, and budget. Consult with a roofing contractor to determine the most suitable replacement option, such as shingle, tile, TPO, EPDM, polyurethan foam or modified bitumen, etc. Proper installation and adherence to building codes are crucial to ensure the longevity and performance of the new roof. The selection of appropriate roofing materials, such as polyurethane foam, TPO, rubber, modified bitumen, or metal, depends on factors such as durability, energy efficiency, and budget.